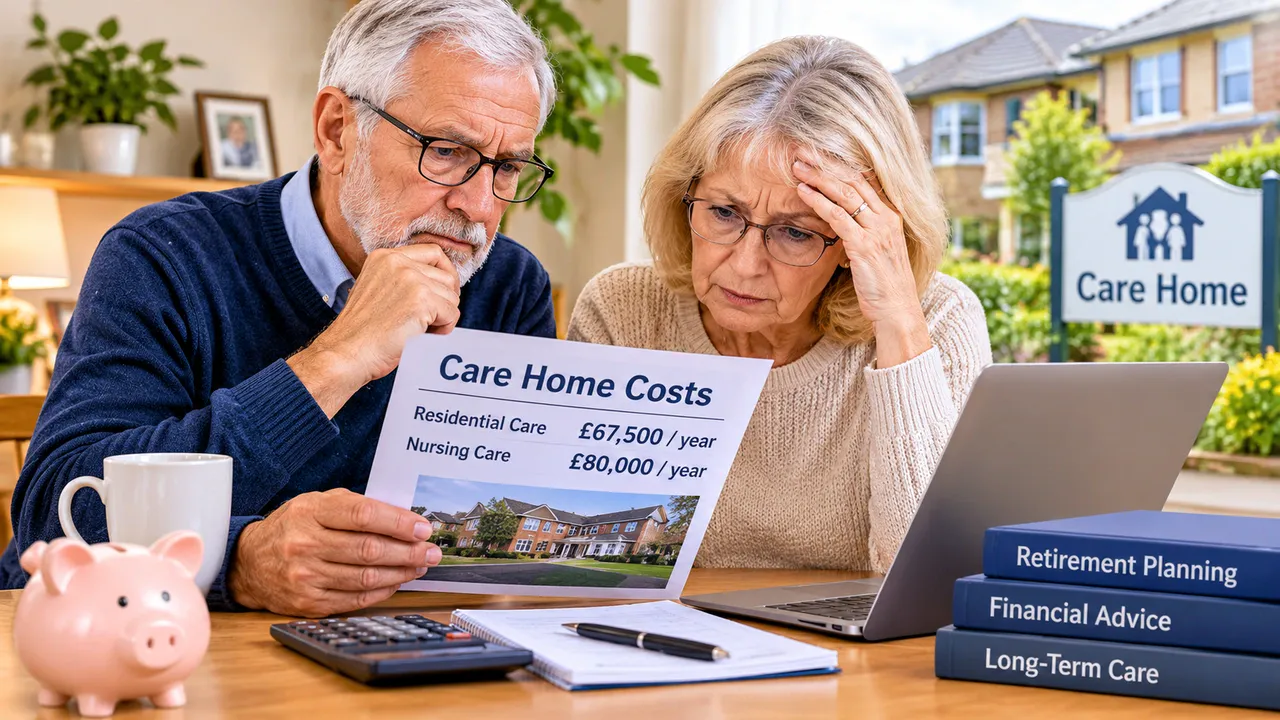
When people picture retirement, they think about holidays, hobbies, time with the grandkids, maybe downsizing and freeing up some cash. Care costs rarely enter the picture. And yet residential care in the UK now averages around £67,500 a year, with nursing care pushing closer to £80,000.
In London and the South East, those numbers go even higher, and because the government scrapped its proposed £86,000 lifetime cap on care costs in England before it took effect, there’s currently no ceiling on what someone will end up paying. Families who don’t plan for this will find their savings wiped out in just a few years.
What Care Costs Really Look Like
A stay in residential care lasting two and a half years, which is about the UK average, will run to around £169,000. Nursing care costs more. Over the same period, that figure creeps closer to £197,000, and where dementia is a factor, both the price and the expected duration tend to increase. Fees haven’t stayed still, either. In some areas, care home costs have gone up by 5% to 10% a year on the back of staffing shortages and higher wages.
By the time a couple now in their mid-sixties actually needs care, likely 15 or 20 years from now, their bill could easily have doubled, which turns an already large expense into something that will genuinely wreck an unprepared retirement plan. Nobody knows if they’ll ever need a care home. Some people won’t, while others will stay for six years or more, and no one can reliably predict which group someone falls into.
The Conflict Between Gifting and Keeping a Reserve
Retirement planning pulls in two directions here. Plenty of people want to pass wealth to their children or grandchildren while they’re still alive, partly because gifts made more than seven years before death fall outside the estate for inheritance tax. That’s a big incentive to give early. But every pound given away is a pound that won’t be there to cover care costs. If a local authority decides someone has deliberately reduced their assets to qualify for state-funded care, they can treat those gifts as still belonging to that person. It’s called “deprivation of assets”, and it happens far more often than people think.
Hold back “just in case,” and the inheritance tax bill could end up larger than it needed to be. Give too generously, and there might not be enough left when a care bill arrives, so the balance between gifting and keeping a reserve needs careful thought.
Good retirement planning advice will treat care and inheritance as one problem, not two separate ones. That means building a plan flexible enough so that a family can respond to whichever scenario they end up facing without getting caught short on the other side. In practice, that usually involves running through what happens to the estate if care lasts two years, five years, or longer, and checking whether the gifting strategy still holds up under each one. It’s the kind of thing that needs revisiting every few years, because care fees don’t stay where they are and neither do people’s circumstances.
Funding Options Most Families Don’t Consider
Once care costs land, most families default to paying from savings or selling the home. There are other options. They don’t get the attention they deserve, and by the time most families learn about them, it’s often too late to use them properly.
Deferred payment agreements buy time. The local authority covers the care fees while a legal charge goes on the property, and the debt gets repaid when the home eventually sells or from the estate. It’s not free, but it avoids a forced sale at the worst possible moment.
With immediate needs annuities, the arrangement works differently. Someone pays a lump sum to an insurer, and in return the insurer guarantees to cover their care fees for the rest of their life, removing the risk of a long stay draining the entire estate. Expensive upfront, yes, but it brings certainty that’s hard to get any other way.
NHS Continuing Healthcare deserves a mention too. If someone’s care needs are primarily health-related, the NHS could fund the full cost; while the eligibility criteria are strict, this option is missed far more often than it should be.
Don’t Wait for the Crisis
Most families avoid the care conversation until someone has already had a fall or received a diagnosis, and by that point the choices are narrow, and the pressure is enormous. That’s leaving it too late. Building care costs into a retirement plan from the start means someone can model different scenarios, stress-test their income against a care need that lasts three years or five or longer, check that the gifting strategy and care reserve don’t pull against each other, and revisit the numbers regularly as fees change.
Starting the conversation early matters more than getting it perfect. Families who’ve already mapped out their options and tested different scenarios will come through with far less stress and far more of their wealth intact than those who act only once a crisis is at the door.
As with any investment, values can move in both directions, and income payments may vary too. You may get back less money than you invested. Past performance does not assure future performance. For more information, visit our website.