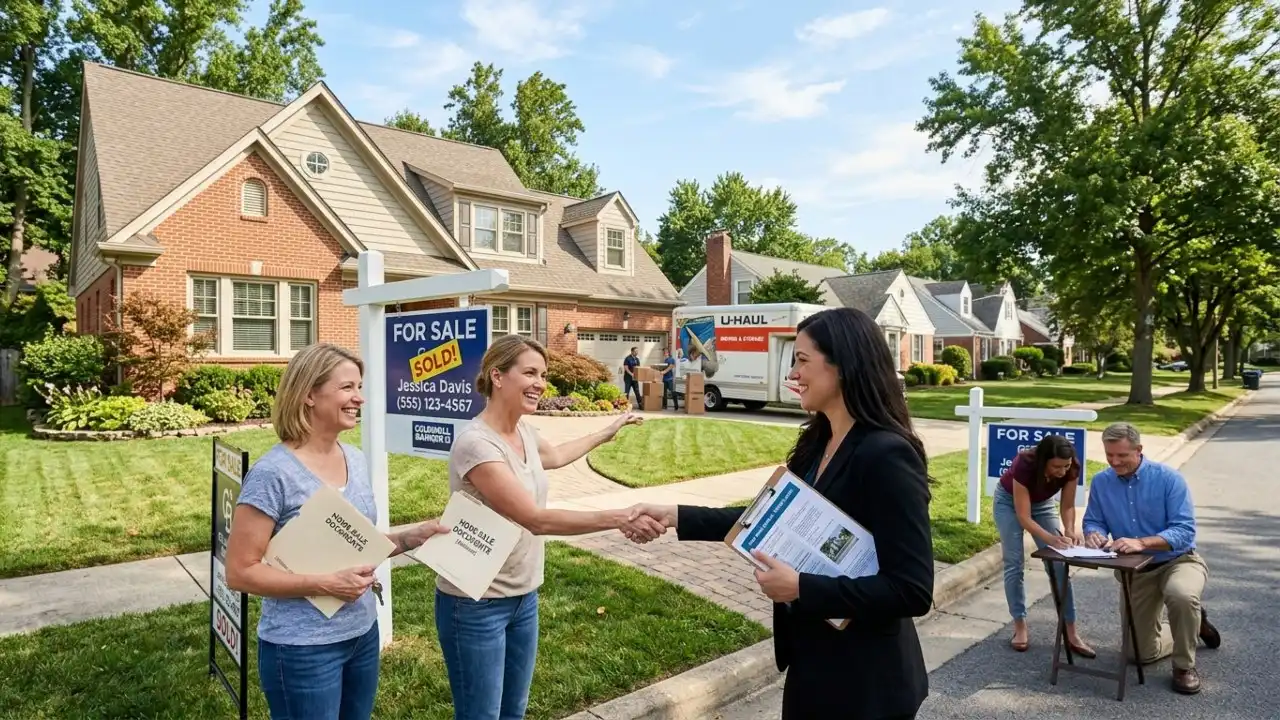
Moving home is an exciting opportunity to find a property that better suits your lifestyle, family or financial circumstances. However, deciding whether to sell your current home before buying another can make the process feel complicated. From managing your finances and finding the right property to coordinating completion dates, there are several factors to consider before making a decision.
Selling before buying can offer greater financial certainty and put you in a stronger position when making an offer on your next home. However, it may also mean arranging temporary accommodation if your sale completes before your purchase is ready.
Understanding the advantages, potential challenges and practical steps involved can help you make an informed decision and enjoy a smoother move.
Myth 1: You Must Find Your Next Home Before Selling Your Current Property
One common misconception is that you should find your next property before putting your existing home on the market. Although this may seem like the most convenient approach, it can create unnecessary pressure.
The reality: Selling first can give you a clearer picture of your available budget. Once your property has sold, you will have a better understanding of the equity you can put towards your next home, subject to outstanding mortgage repayments, selling costs and other expenses.
You can also approach estate agents and mortgage lenders with a more defined financial position. This may make you a more attractive buyer, particularly to sellers who prefer buyers who are not dependent on completing another sale.
However, selling first does not mean you must stop looking for properties. Researching the market, arranging viewings and identifying suitable areas before your sale completes can help you move quickly when the right home becomes available.
Myth 2: Selling First Always Means You Will Have Nowhere to Live
The possibility of being without a permanent home between transactions is one of the biggest concerns for homeowners considering selling before buying.
The reality: A gap between your sale and purchase is possible, but it is not inevitable. Careful planning and communication can help you minimise the risk.
Ideally, your estate agent and solicitor will work with the relevant parties to coordinate the sale and purchase completion dates. However, property chains can be unpredictable, and there is no guarantee that both transactions will complete on the same day.
If your sale completes before you can move into your new property, consider arranging temporary accommodation with family, booking short-term accommodation or renting a property for a limited period.
You should also plan for the practicalities of moving twice. Storage fees, removal costs and temporary accommodation can increase your overall moving budget.
Before committing to a sale, calculate these potential expenses and decide how much flexibility you can afford. Having a contingency plan can reduce stress if your timelines change unexpectedly.
Myth 3: You Will Lose Your Next Home If You Sell Before Buying
Some homeowners worry that selling first means they will miss out on their preferred property while waiting for their own transaction to complete.
The reality: This risk exists, but selling first can also strengthen your position when making an offer.
A buyer who has already sold their property, or whose sale is progressing well, may be more appealing to a seller than someone whose purchase depends on finding a buyer for their existing home. However, sellers will also consider factors such as mortgage approval, the length of the chain and the proposed completion date.
To improve your chances, start researching the market before your property sells. Register with local estate agents, establish your preferred locations and understand the typical asking prices for suitable properties.
If you are considering a move in Tonbridge, speaking to experienced estate agents in Tonbridge can help you understand local property availability, pricing and the likely timescales involved in buying and selling.
Keep your mortgage agreement in principle up to date and have your identification, proof of funds and other necessary documents ready. Being organised can help you act promptly when a suitable property comes onto the market.
Myth 4: Selling Your Home First Means You Will Have More Money to Spend
Selling your current property can make your next purchase easier to plan, but it does not automatically mean you will have a larger budget.
The reality: The amount available for your next home depends on the equity released from your sale and the costs associated with moving.
Start by estimating your property’s likely sale price. Deduct your outstanding mortgage balance, estate agency fees, solicitor’s fees, any applicable early repayment charges and other selling expenses.
You should then account for the costs of buying your next home, including conveyancing, surveys, removals and any applicable Stamp Duty Land Tax in England or Land Transaction Tax in Wales.
For example, if your sale releases £100,000 in equity after repaying your mortgage, that amount is not necessarily your entire deposit budget. You may need to reserve part of it for transaction costs, repairs, furnishings and unexpected expenses. If your sale completes before your purchase, comparing current savings rates can help that money earn interest while you wait.
It is also worth speaking to a mortgage adviser before committing to your next purchase. Your borrowing capacity may change depending on your income, expenditure, credit profile and the mortgage products available when you apply.
A realistic budget will help you avoid stretching your finances too far.
Myth 5: You Can Easily Coordinate the Sale and Purchase Completion Dates
Many homeowners assume that the sale of their existing property and the purchase of their new home can be completed on the same day without difficulty.
The reality: Coordinating two transactions requires communication between buyers, sellers, solicitors, mortgage lenders and estate agents. Delays can occur if searches, mortgage arrangements or legal enquiries remain outstanding.
In a property chain, your completion date may also depend on several other transactions progressing successfully.
Once you have accepted an offer on your property, keep your solicitor informed about your plans for the onward purchase. Similarly, tell the estate agent handling your purchase that your preferred completion date depends on the sale of your existing home.
Avoid making non-refundable arrangements, such as booking removals, until your solicitor confirms that completion is sufficiently certain. Even then, retain some flexibility in case circumstances change.
A coordinated approach will not eliminate every risk, but it can help you identify potential problems early and respond more effectively.
Myth 6: Renting Temporarily Between Moves Is Always a Bad Idea
The thought of selling, renting and then buying again may seem inconvenient and expensive. As a result, some homeowners dismiss temporary renting without considering its potential benefits.
The reality: Renting between moves can provide flexibility, particularly if you need time to find the right property or want to avoid rushing into a purchase.
Without the pressure of completing an onward purchase immediately, you may be able to explore different neighbourhoods, assess commuting arrangements or wait for a property that better meets your requirements.
However, temporary renting involves additional costs. You may need to pay rent, a tenancy deposit, removal fees and storage charges while your belongings are between homes. You should also check the tenancy terms, including the notice period and any restrictions that could affect your plans.
Compare these expenses with the potential cost of losing a suitable property or making a rushed buying decision. For some households, renting temporarily offers valuable breathing space; for others, coordinating the transactions more closely may be preferable.
The right choice depends on your budget, family circumstances and willingness to move more than once.
How to Prepare for Selling Before Buying
If you decide to sell first, taking a few practical steps can make the process more manageable.
- Arrange a property valuation: Obtain an informed estimate of your home’s market value and discuss a realistic asking price.
- Review your mortgage: Check your outstanding balance, repayment conditions and whether porting your existing mortgage is possible.
- Calculate your moving budget: Include legal fees, agency fees, taxes, removals, temporary accommodation and contingency funds.
- Research the buying market: Identify suitable areas, property types and realistic price ranges before your sale completes.
- Prepare your paperwork: Gather relevant property documents and financial information to help avoid unnecessary delays.
- Stay in regular contact: Keep your estate agent, solicitor and mortgage adviser informed as your circumstances develop.
Taking these steps early can help you make decisions with greater confidence and reduce the likelihood of unexpected complications.
Conclusion
Selling your current property before buying a new home can provide financial clarity, strengthen your position as a buyer and give you greater control over your next move. However, it also requires careful planning, particularly when it comes to completion dates, temporary accommodation and the costs associated with moving.
The key is to understand your priorities, establish a realistic budget and prepare for the possibility that your sale and purchase may not align perfectly. Researching the market early and maintaining open communication with your estate agent and solicitor can make a significant difference.
Whether you are moving locally or relocating to a different area, taking a considered approach will help you find a property that suits your needs without putting unnecessary pressure on your finances. With the right preparation, selling before buying can be a practical and rewarding route towards your next home.